
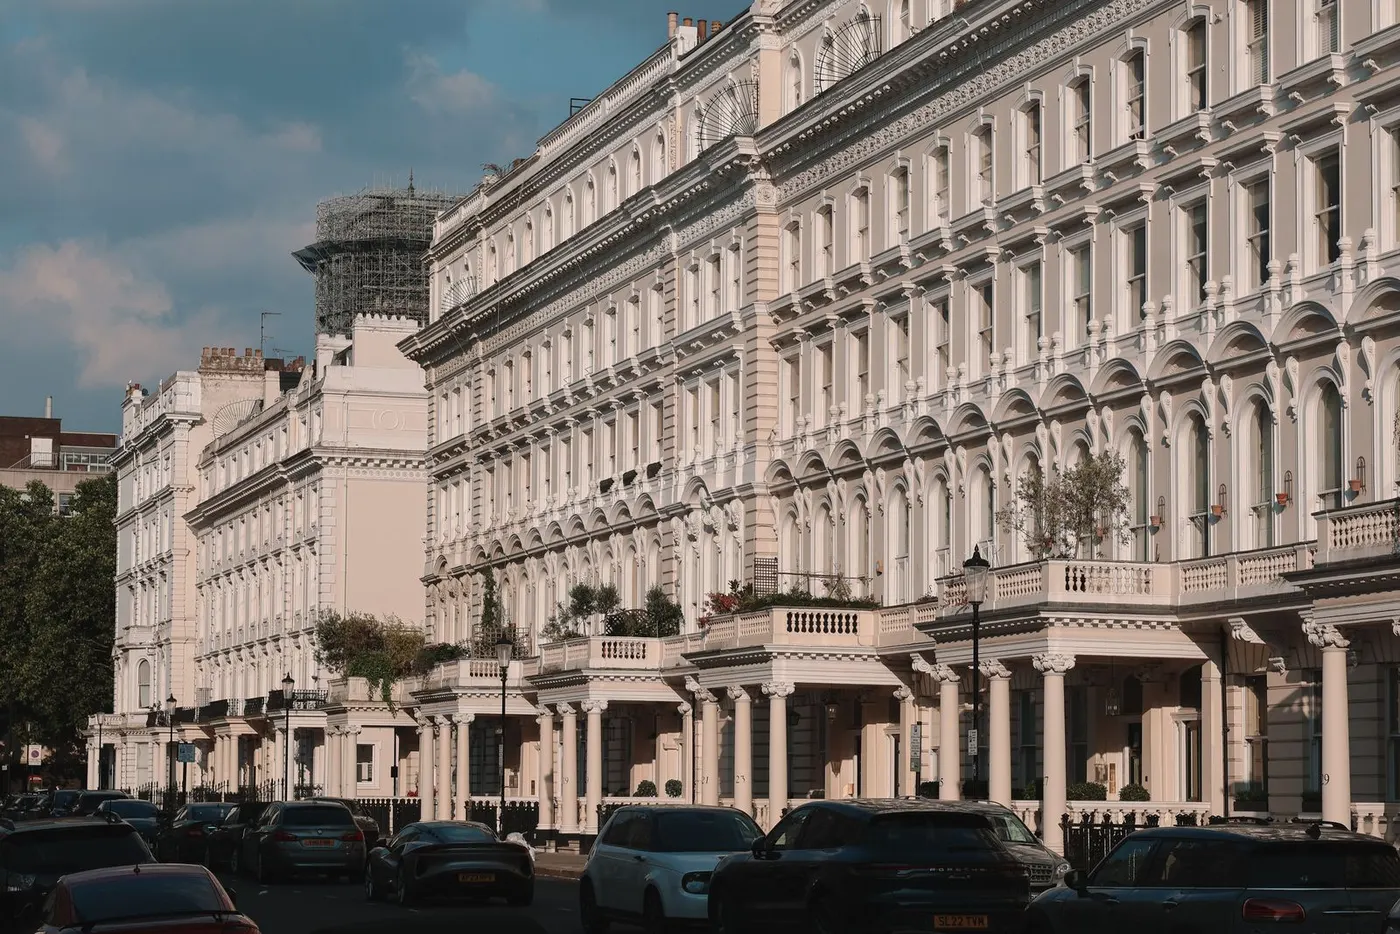
The government has announced a surcharge from April 2028 on owners of residential property in England worth £2 million or more, in four bands from £2,500 to £7,500 a year. Because it falls on the owner rather than the occupier, a let property means the landlord pays it.
Article · 28 July 2026
Council tax is normally the occupier's bill. The High Value Council Tax Surcharge announced for April 2028 is not. It is to be levied on the owner of a residential property in England worth £2 million or more, which means that where the property is let, the charge falls on the landlord rather than on the tenant.
The published design has four bands: £2,500 a year for a property valued at £2 million to £2.5 million, £3,500 for £2.5 million to £3.5 million, £5,000 for £3.5 million to £5 million and £7,500 above £5 million. Values are based on 2026, the charges rise with CPI inflation each year from 2029/30, and revaluations take place every five years. First bills are to be issued in March 2028. The government expects fewer than 1% of properties in England to be above the £2 million threshold.
The detail was put out for consultation from 19 May to 14 July 2026, and the government is now analysing the responses. The detail is not settled law, and the final shape is for the government to confirm and for Parliament to legislate. The date, the bands and the amounts above are the government's own published figures, and they are enough to plan around.
A tenant paying council tax on a £2.5m house absorbs the ordinary band charge as part of the cost of living there. A surcharge levied on the owner does not work that way. It arrives as an annual cost of holding the asset, in the same category as ground rent, buildings insurance or a service charge, and it is payable whether the property is occupied, void or between tenancies.
There are only two places for it to go: the landlord's return, or the rent. And the route to the rent is narrower than it was, because since 1 May 2026 rent increases in the private rented sector are limited to once a year with at least two months' notice under Phase 1 of the Renters' Rights Act. A charge that appears on a bill in March 2028 cannot be recovered through rent until the next permitted review, and then only with notice.
Take a let house in England valued at £2.4 million, producing £4,500 a month in rent. The figures are illustrative.
Each band boundary is a step, not a taper. A property valued at £4.9m pays £5,000 a year and one valued at £5.1m pays £7,500, so £200,000 of assessed value makes a £2,500 a year difference. The steps at £2.5m and £3.5m are £1,000 and £1,500. With revaluations every five years, a property sitting just under a boundary can cross it without anything happening to the property at all, which makes the valuation, and the way to challenge it, worth understanding.
A landlord holding a high-value property through a company is already inside a separate annual regime. The Annual Tax on Enveloped Dwellings is payable mainly by companies owning UK residential property valued over £500,000, and it also catches partnerships with a corporate partner and collective investment schemes.
The chargeable amounts for 1 April 2026 to 31 March 2027 are:
| Property value | Annual charge |
|---|---|
| £500,001 to £1m | £4,600 |
| £1m to £2m | £9,450 |
| £2m to £5m | £32,200 |
| £5m to £10m | £75,450 |
| £10m to £20m | £151,450 |
| Over £20m | £303,450 |
ATED reliefs and return mechanics are a separate subject and are not set out here — whether a particular company actually pays depends on them, and they are worth establishing properly rather than approximately. The point for this article is that the surcharge and ATED are two different charges, assessed on different bases by different bodies, capable of applying to the same house. A company holding a £2.4m let property is looking at an ATED band of £32,200 for 2026/27 before relief, and a £2,500 surcharge from April 2028 on top of whatever survives that analysis.
The surcharge turns entirely on assessed value, with revaluations every five years and a step up in the charge at £2.5m, £3.5m and £5m. For a landlord holding a property near one of those boundaries, or near £2m, the valuation decides the whole liability. Whatever challenge process the final design provides, knowing where each property sits against the four bands well before March 2028 leaves time to use it.
A landlord with a £2m-plus let property in England is in the middle of several changes at once, and they compound rather than alternate.
None of those is a reason to do anything in particular with a property, and this site does not give investment advice. They are reasons to know your actual net yield per property rather than your gross one, because every item on that list moves the net figure and none of them moves the gross.
For company-held property, property company accounts and accountants for property companies and SPVs cover the annual cycle including ATED. If the surcharge is prompting a wider look at how the property is held, the incorporation guide sets out the real costs on both sides, and capital gains tax on rental property covers what happens on a sale. This is information about an announced measure, not advice on what to do with a specific property.
What has changed in landlord tax, the dates coming up, and one number worth checking on your own portfolio.
The owner of the property, not the occupier. That is the feature that makes it matter to landlords, because ordinary council tax on a let property is usually the tenant's bill during a tenancy while this surcharge is levied on ownership. It is therefore payable whether the property is occupied, void or between tenancies, in the same way as buildings insurance or a service charge. The announced design applies to residential property in England valued at £2 million or more, in four bands from £2,500 to £7,500 a year, with first bills issued in March 2028 and revaluations every five years.
It is announced rather than enacted. The design consultation ran from 19 May to 14 July 2026, the government has to confirm the final design, and Parliament has to legislate for it before anything is charged. What is published is specific: April 2028, England, £2 million and above, £2,500 a year up to £2.5 million, £3,500 up to £3.5 million, £5,000 up to £5 million and £7,500 above that, first bills in March 2028, and revaluations every five years. Those figures are firm enough to model into a net yield, while the detail of valuation, reliefs and challenge routes could still change. Treat it as a planning assumption, not as a current liability.
Only through rent, and only within the constraints that now apply to rent. Since 1 May 2026, Phase 1 of the Renters' Rights Act limits rent increases in the private rented sector to once a year with at least two months' notice, and that applies to existing tenancies as well as new ones. So a surcharge appearing on a bill in March 2028 cannot be recovered until the next permitted review, with notice given at least two months before it takes effect. On an illustrative £2.4m let producing £54,000 of gross rent a year, the £2,500 surcharge is 4.6% of gross rent, so recovering it in full is a visible increase rather than a rounding.
They are two separate charges capable of applying to the same house. The Annual Tax on Enveloped Dwellings is payable mainly by companies owning UK residential property valued over £500,000, and also catches partnerships with a corporate partner and collective investment schemes. For 1 April 2026 to 31 March 2027 the charges run from £4,600 for properties between £500,001 and £1m up to £303,450 above £20m, with £32,200 for the £2m to £5m band. Whether a particular company pays depends on the reliefs and return requirements, which are a subject in their own right and worth establishing precisely rather than assuming either way.
Each boundary is a step rather than a taper. A property assessed at £4.9m carries £5,000 a year and one assessed at £5.1m carries £7,500, so £200,000 of assessed value makes a £2,500 annual difference. The charge also steps from £2,500 to £3,500 at £2.5m and from £3,500 to £5,000 at £3.5m. At the £2m line, crossing it moves a property from nothing to £2,500 a year. With revaluations every five years, a property can cross a boundary without anything happening to the property itself. Knowing where each property sits against the four bands well before bills are issued in March 2028 is the practical response.
A licensed practice of the Association of Accounting Technicians through Peter Allen MAAT, licence 1001556. ICPA members. Supervised for anti-money-laundering purposes by HMRC. Professional indemnity insurance in place.
 AAT licensed
 ICPA member
 Xero Gold Partner
 FreeAgent Partner
Tell us what you own and how it is held. We reply within one working day with where your tax stands and a fixed monthly fee.
One short email: what has changed in landlord tax, the dates coming up, and one number worth checking in your own figures.